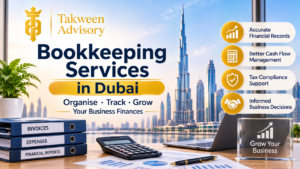
Maintaining accurate financial records is essential for every business, regardless of its size or industry. From recording daily transactions to tracking expenses and monitoring cash flow, organised bookkeeping helps business owners understand their financial position and make informed decisions. In Dubai, where companies must also consider UAE VAT and corporate tax obligations, maintaining reliable accounting records has become an important part of business management.
Professional Bookkeeping services help businesses organise financial information, monitor transactions, and maintain records that support reporting and compliance requirements. Whether you operate a startup, small business, consultancy, or established company, an effective bookkeeping system can improve financial visibility. Takween Advisory helps businesses understand financial administration requirements and explore suitable support for their bookkeeping needs in the UAE.
What Are Bookkeeping Services?
Bookkeeping is the systematic recording and organisation of a company’s financial transactions. It involves documenting income, expenses, purchases, sales, payments, and receipts to maintain an accurate record of business activities.
Professional bookkeeping services may include:
- Recording daily financial transactions.
- Maintaining sales and purchase records.
- Tracking accounts payable and receivable.
- Preparing bank reconciliations.
- Organising invoices and payment receipts.
- Monitoring business expenses.
- Maintaining general ledgers.
- Preparing basic financial reports.
- Supporting VAT and corporate tax record preparation.
Bookkeeping provides the financial information that businesses and accounting professionals use to prepare financial statements, review performance, and meet relevant reporting obligations.
Why Are Bookkeeping Services Important for UAE Businesses?
Businesses in Dubai operate in a competitive commercial environment where financial organisation can influence operational efficiency and long-term planning. Proper bookkeeping offers several practical benefits.
1. Accurate Financial Records
Recording transactions consistently helps businesses maintain a clear history of their financial activities. It also makes it easier to locate invoices, verify payments, and review business expenses.
2. Better Cash Flow Management
Cash flow is important for paying suppliers, employees, rent, and other operating expenses. Bookkeeping helps business owners monitor incoming and outgoing payments, identify overdue invoices, and plan upcoming financial commitments.
3. Improved Business Decisions
Organised financial records provide useful information about revenue, costs, and profitability. Business owners can use this information to evaluate expenses, review pricing, and identify opportunities for improvement.
4. Support for Tax Compliance
Businesses may need financial records to support VAT returns, corporate tax calculations, and other applicable obligations. Accurate bookkeeping helps maintain an audit trail and makes it easier to retrieve relevant supporting documents.
5. Reduced Administrative Pressure
Maintaining financial records regularly can prevent paperwork from accumulating. It also makes financial reviews and year-end preparation more manageable.
Key Bookkeeping Services for Companies in Dubai
The services required by a business depend on its size, transaction volume, industry, and internal accounting arrangements.
Daily Transaction Recording: Income, expenses, purchases, sales, and payments are recorded in the appropriate accounts to maintain updated financial information.
Accounts Payable Management: Supplier invoices and outstanding payments are organised so businesses can monitor their liabilities and payment schedules.
Accounts Receivable Tracking: Customer invoices, collections, and overdue balances are monitored to support timely payments and cash flow planning.
Bank Reconciliation: Bank statements are compared with internal accounting records to identify differences, missing transactions, or incorrect entries.
Expense Management: Business expenses are categorised and documented to help owners understand operating costs and maintain supporting evidence.
Financial Reporting Support: Bookkeeping records can be used to prepare summaries of income, expenditure, cash flow, and other financial information for management review.
Tax Record Organisation: Relevant invoices, transaction records, and supporting documents are organised to assist with VAT and corporate tax reporting.
How Does the Bookkeeping Process Work?
A structured bookkeeping process helps maintain consistency and accuracy throughout the financial year.
Step 1: Understand the Business
The process begins with reviewing the company’s activities, transaction volume, accounting requirements, and existing financial records. This helps determine the bookkeeping system and reporting approach required.
Step 2: Collect Financial Documents
Relevant documents may include sales invoices, supplier bills, bank statements, receipts, payroll records, expense claims, and payment confirmations.
Step 3: Record Transactions
Financial transactions are entered into an accounting system and categorised under appropriate accounts. Accurate descriptions and supporting documents help maintain reliable records.
Step 4: Reconcile Financial Accounts
Bank and other relevant account balances are compared with the bookkeeping records. Differences are investigated and corrected where necessary.
Step 5: Review Financial Information
Regular reviews help identify unusual expenses, missing invoices, outstanding customer payments, and other issues that may require attention.
Step 6: Prepare Reports and Maintain Records
Financial summaries are prepared for management review, while supporting documents are organised and retained according to applicable legal requirements.
Bookkeeping and UAE Tax Compliance
Bookkeeping plays an important role in supporting UAE tax compliance. Businesses registered for VAT need appropriate records of taxable supplies, purchases, input tax, output tax, and supporting invoices.
Companies subject to UAE corporate tax must also maintain records and documents that support the information reported in their tax returns. Under the UAE Corporate Tax Law, relevant records generally need to be retained for at least seven years following the end of the applicable tax period.
Good bookkeeping does not automatically guarantee tax compliance. Businesses should ensure that their records reflect the applicable tax rules and seek qualified tax advice where necessary. Bookkeeping, tax advisory, tax return preparation, and statutory auditing are distinct services and may have separate professional requirements.
Common Bookkeeping Mistakes Businesses Should Avoid
Some companies struggle with financial administration because records are updated irregularly or supporting documents are not properly organised. Common mistakes include mixing personal and business transactions, overlooking small expenses, delaying bank reconciliations, recording incorrect transaction categories, and failing to maintain complete invoices.
Businesses should also avoid relying entirely on manual spreadsheets without suitable review procedures. Accounting software, consistent document management, and periodic checks can help improve record accuracy.
How Takween Advisory Supports Bookkeeping Requirements
Managing financial documentation can be challenging for entrepreneurs who want to focus on business development and daily operations. Takween Advisory helps businesses understand bookkeeping requirements and organise the administrative steps involved in maintaining financial records.
From understanding transaction documentation to coordinating suitable accounting support, businesses can receive guidance on establishing a more structured financial management process.
Whether you are launching a new company, managing a growing SME, or improving the financial administration of an established organisation, proper bookkeeping can support better control over business finances.
Conclusion
Professional Bookkeeping services are valuable for businesses seeking accurate financial records, improved cash flow visibility, and organised tax documentation. By recording transactions consistently, reconciling accounts, tracking expenses, and maintaining supporting documents, companies can develop a clearer understanding of their financial position.
For businesses operating in Dubai, effective bookkeeping also supports preparation for relevant VAT and corporate tax responsibilities. With guidance from Takween Advisory, business owners can better understand their bookkeeping requirements and build an organised approach to financial administration in the UAE.