When a family’s finances start to fall apart, the house is often the first thing on everyone’s mind. Can it be kept? What is it actually worth? Will the court see the same number the homeowner sees?
These questions come up often, and they explain why Bankruptcy Appraisal Services in Chino Hills, CA play a larger role than most people expect. A bankruptcy case depends on accurate numbers, and real estate is usually the largest asset involved.
This article explains what a bankruptcy appraisal is, why it matters, how it compares to probate work, and what homeowners and attorneys typically run into along the way.
Why Property Value Sits at the Center of Bankruptcy
Every bankruptcy filing requires the debtor to list their assets and assign each one a value. For most homeowners, the home is the biggest line on that list.
That figure isn’t a formality. It shapes which assets are protected, what creditors may be entitled to, and in some cases whether a property has to be sold.
Many people are tempted to pull a number from an online estimate. The problem is that automated tools can’t see a cracked foundation, a dated kitchen, or a recent remodel. Bankruptcy trustees know this, and they often question values that don’t have solid support behind them.
The Role of the Homestead Exemption
California’s homestead exemption protects a set amount of a homeowner’s equity in a primary residence. The exemption was expanded significantly in recent years, with protection tied to county median home prices within set limits.
Because the exemption covers equity, not the full home value, the appraised value directly affects how much equity is exposed. A value set too high can make it look like there’s more unprotected equity than really exists. A value set too low can draw scrutiny from the trustee.
Key takeaway: In a bankruptcy, the home’s value isn’t just a number on a form. It can decide whether a family keeps its home.
What a Bankruptcy Appraisal Actually Involves
A bankruptcy appraisal is a professional, written opinion of value prepared by a licensed appraiser. It looks a lot like a standard home appraisal, but its purpose and timing are different.
Valuing the Property as of a Specific Date
Most bankruptcy appraisals are tied to the date the petition was filed. If the appraisal is ordered weeks or months later, the appraiser may need to prepare a retrospective valuation that looks back to that earlier date.
That means studying sales that closed around the filing date, not just what’s selling today. In a market where prices shift quickly, that distinction can change the result by a meaningful amount.
Looking at the Home’s Real Condition
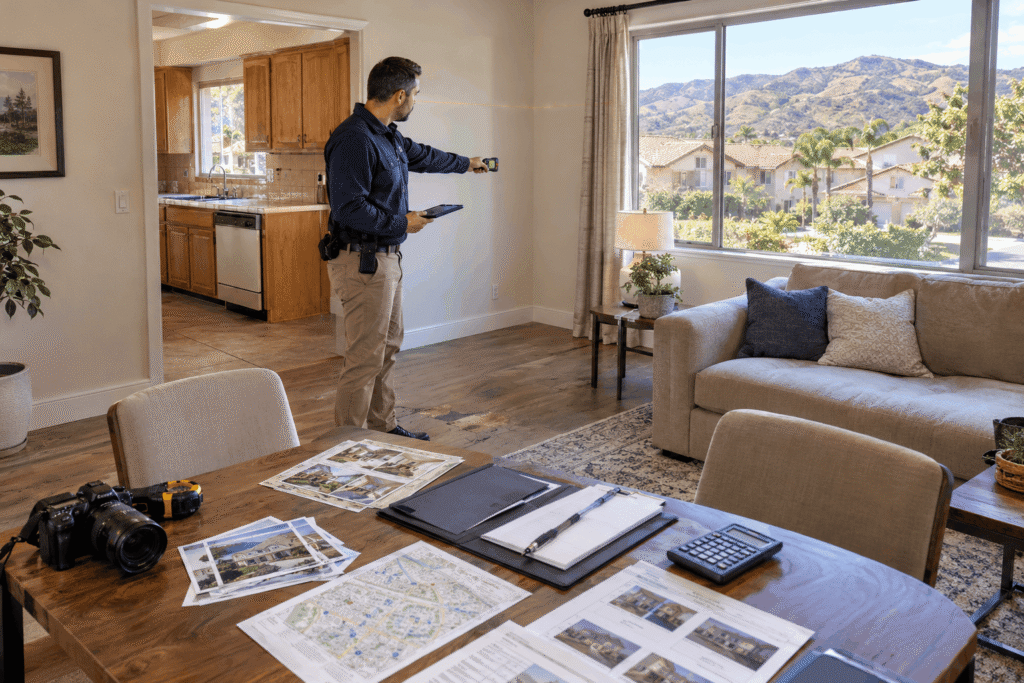
A trained appraiser walks through the property and notes things a database never captures. Roof wear, outdated systems, water damage, and deferred maintenance all lower value.
Upgrades count too. A new HVAC system or a remodeled bathroom can raise value, and fair reporting reflects both sides.
Producing a Report That Holds Up
The final report explains the method, lists comparable sales, and shows how adjustments were made. That paper trail is what gives the value credibility with trustees, creditors, and judges.
In a community like Chino Hills, CA, where neighborhoods range from hillside estates to tract homes and equestrian properties, choosing truly comparable sales takes local knowledge. A home with acreage and horse facilities can’t be fairly compared to a standard lot down the street.
The Benefits of Getting an Independent Valuation
The biggest advantage of a professional appraisal is defensibility. When a value is backed by a detailed report, it’s much harder for anyone to dispute without their own evidence.
It also brings clarity to decision-making. Attorneys use appraised values to decide between Chapter 7 and Chapter 13, to estimate exemption coverage, and to plan repayment terms. Guesswork in those early choices can lead to costly surprises later.
Supporting Chapter 13 Plans
In Chapter 13 cases, property value can affect how much must be paid to unsecured creditors. It can also matter in disputes over second mortgages or secured loans, where the home’s value compared to the debt carries real weight.
An accurate appraisal helps build a repayment plan that’s realistic, not one based on a number that might collapse under review.
Reducing Conflict and Delays
Value disputes slow cases down. When a trustee or creditor challenges a number, it can trigger more paperwork, more hearings, and more legal fees.
A well-supported appraisal from the start often prevents that back-and-forth. It doesn’t guarantee agreement, but it gives everyone the same factual starting point.
How Bankruptcy and Probate Appraisals Compare
Appraisers who handle bankruptcy work often handle estate work as well, since both rely on court-ready reporting and specific valuation dates. Families who search for a Probate Appraisal Service in Chino, CA are usually dealing with a loved one’s passing rather than financial hardship, but the technical demands are similar.
In probate, the key date is typically the date of death. That value helps establish the inherited property’s tax basis, which can matter a great deal when heirs later sell.
California probate cases also involve a court-appointed probate referee who values many estate assets. Even so, executors and heirs often seek an independent appraisal for tax planning, trust administration, or settling disagreements between family members.
The two fields overlap in another way too. Some estates are insolvent, and some people pass away during an active bankruptcy. In those cases, both timelines and both sets of rules may come into play.
Real-World Situations Where an Appraisal Makes a Difference
The value of a professional appraisal is easier to see through everyday examples.
The Family Trying to Keep Their Home
Picture a couple who bought their home over a decade ago. After a job loss and mounting medical bills, they consult a bankruptcy attorney. Their main concern is whether they’ll lose the house.
A careful appraisal shows the home needs a new roof and has an outdated interior. The final value lands below what online tools suggested, and their equity falls within the homestead exemption. That single report gives them the confidence to move forward.
The Small Business Owner With Mixed Assets
A local business owner files for bankruptcy with a primary home and a small rental property. Each one is treated differently under the law.
Separate valuations help the attorney show which equity is protected and which may be available to creditors. Without them, the case could stall over arguments about worth.
The Estate That Meets a Bankruptcy Case
An adult child is named executor of a parent’s estate, only to learn a sibling who inherits a share has filed for bankruptcy. Suddenly, the inherited interest becomes part of the sibling’s case.
Here, a date-of-death value matters for the estate, and the sibling’s share matters for the bankruptcy. Situations like this show why families sometimes look for a Probate Appraisal Service in Chino, CA that also understands bankruptcy timelines.
Choosing a Qualified Appraiser
Not every appraiser takes on litigation or court-related work. It’s worth asking about experience with bankruptcy and probate assignments, retrospective valuations, and testimony if a dispute ends up in front of a judge.
Local experience matters as well. Firms that work regularly across the Inland Empire, such as Cal Best Appraisal, tend to be familiar with how neighborhoods in Chino Hills, CA differ from one block to the next.
Licensing should always be confirmed through the California Bureau of Real Estate Appraisers. A valid license and a clear, well-documented report are the two most important signs of a reliable valuation.
Final Thoughts
Bankruptcy is stressful, and the questions around a family home make it even harder. A professional appraisal won’t fix financial trouble, but it replaces uncertainty with facts.
For homeowners and attorneys alike, an accurate, well-supported value is one of the most practical tools in any bankruptcy or estate case. Anyone facing either situation is well served by getting a credible appraisal early in the process.
FAQs
Do I need an appraisal to file for bankruptcy?
An appraisal isn’t always legally required, but debtors must list a fair value for their property. A professional appraisal gives that number solid support if a trustee or creditor questions it.
How much does a bankruptcy appraisal cost?
Costs vary based on the property type, size, and whether a retrospective date is needed. Most single-family home appraisals fall in the range of a few hundred dollars, while complex properties cost more.
What is a retrospective appraisal?
A retrospective appraisal estimates a property’s value as of a past date, such as a bankruptcy filing date or date of death. It relies on market data from that earlier period.
Can a bankruptcy trustee challenge my home’s value?
Yes. Trustees can question a value they believe is too low and may order their own appraisal. A detailed report from a licensed appraiser makes the original value easier to defend.
Is a probate appraisal the same as a bankruptcy appraisal?
They use similar methods but serve different purposes. Probate appraisals usually focus on the date of death, while bankruptcy appraisals typically focus on the petition filing date.