Deciding to close a business can feel challenging for any company owner. You might be retiring, changing careers, or moving towards another opportunity. Whatever your reasons, understanding the process helps you avoid unnecessary complications.To dissolve a company, you must follow the correct legal procedures. In the UK, company dissolution usually involves applying to Companies House. However, your company must meet specific eligibility requirements before applying.Choosing the wrong closure method could create financial and legal problems. Therefore, understanding your options is essential before taking further action.This guide explains how to strike off a company in the UK. It covers eligibility, preparation, application steps, costs, and common mistakes. You will also learn when professional advice might be beneficial.
What Does It Mean to Dissolve a Company?
Dissolving a company means removing it from the Companies House register. Once dissolution takes effect, the company no longer legally exists.This process commonly follows a voluntary application for company strike-off. It is often suitable for businesses that have stopped trading. However, dissolution is not appropriate for every company.A company with significant debts may require another closure procedure. Similarly, insolvent businesses might need formal insolvency proceedings.Understanding these differences helps directors choose the correct approach.
What Is Company Strike-Off?
Company strike-off is the process used to remove a company from the register. Directors can apply voluntarily when their company meets the legal requirements.Companies House reviews the application and notifies relevant parties. Interested parties can object if they have legitimate grounds.If no successful objection prevents removal, Companies House publishes the dissolution notice. The company is then removed from the register.
Dissolution Versus Liquidation
Dissolution and liquidation are different processes with different purposes.Dissolution usually closes an inactive company without formal liquidation. Liquidation involves collecting assets and distributing proceeds according to insolvency law.A solvent company may also use a members’ voluntary liquidation. This can be appropriate when substantial assets require an orderly distribution.An insolvent company may require a creditors’ voluntary liquidation. Directors should obtain appropriate professional advice before choosing.
When Should You Dissolve a Company?
Business circumstances vary, so the right decision depends on your situation. Dissolution may suit companies that have permanently stopped operating.For example, you might have completed a project and closed your business. You may also have decided against continuing a limited company.Some owners close companies after restructuring their business activities. Others dissolve dormant companies that no longer serve a useful purpose.However, simply stopping trading does not dissolve a company. Your legal responsibilities generally continue until dissolution takes effect.
Situations Where Strike-Off May Be Suitable
Voluntary strike-off may suit a company that has ceased trading. It may also suit a company with no outstanding business activities.The company must satisfy the applicable statutory conditions. These include restrictions concerning recent trading and certain transactions.Before applying, review your company’s finances, contracts, and outstanding obligations. Ensure the proposed closure complies with Companies Act requirements.
When Strike-Off May Not Be Appropriate
Strike-off is not a shortcut for avoiding creditors. Directors must not use dissolution to escape legitimate financial obligations.A company with unresolved debts could face objections from creditors. Creditors may also seek restoration after dissolution.Recent trading or certain company transactions can affect eligibility. Selling assets or distributing property requires particular care.If insolvency is possible, seek advice from a qualified insolvency practitioner. They can explain suitable procedures and directors’ responsibilities.
Requirements Before You Dissolve a Company
Before applying, confirm that your company qualifies for voluntary strike-off. The rules are important because an incorrect application can cause problems.Under the Companies Act 2006, restrictions apply to recent business activities. Generally, the company must not have traded during the previous three months.It must also avoid certain activities during that period. These include changing its name and carrying on business.There are limited exceptions for specific purposes. These can include activities necessary to conclude the company’s affairs.Your company must not be subject to relevant insolvency proceedings. Certain ongoing arrangements can also prevent a valid application.Check the current statutory requirements before submitting your application.
Settle Outstanding Debts and Obligations
Review all money owed by your company before closure. This includes supplier invoices, loans, taxes, and other liabilities.Contact creditors and agree suitable payment arrangements where necessary. Do not assume dissolution automatically cancels outstanding debts.Directors must consider their duties when handling company finances. Improper asset transfers can create serious legal consequences.If the company cannot pay its debts, seek specialist advice. Formal insolvency procedures may be more suitable.
Deal With Employees and Contracts
If your company employs staff, address employment responsibilities first. This may involve wages, holiday pay, redundancy, and contractual notice.Review leases, subscriptions, supplier agreements, and customer commitments. Cancel or conclude contracts according to their terms.Inform affected parties where appropriate. Keep records of important decisions and payments.
Address Corporation Tax and Other HMRC Responsibilities
Contact HMRC about the company’s tax position. Depending on circumstances, you may need to submit final returns.Corporation Tax liabilities must be settled or properly addressed. You should also review VAT and PAYE obligations.Registering for tax does not automatically end when trading stops. Follow HMRC’s relevant procedures and retain supporting documentation.Confirm that the company’s tax affairs are properly concluded. This can help reduce delays and potential disputes.
How to Strike Off a Company Online
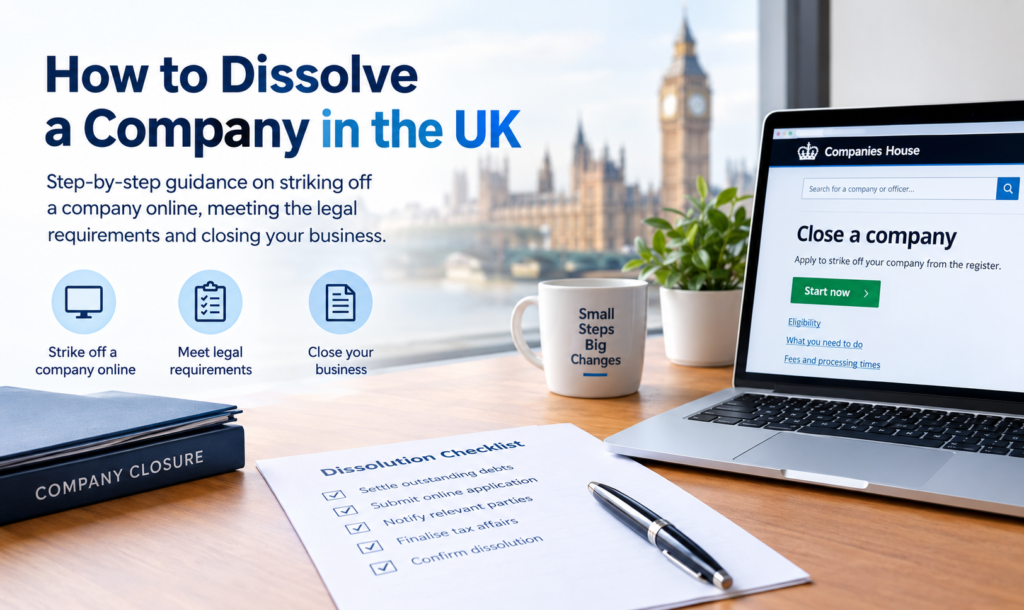
Many eligible companies can apply through the Companies House online service. The process is generally straightforward when company affairs are settled.However, submitting an application is only one part of closure. You must also notify relevant parties and follow statutory requirements.
Step 1: Review the Company’s Eligibility
Start by checking whether voluntary strike-off is legally available. Review recent trading, financial transactions, and any ongoing proceedings.Identify outstanding debts, tax liabilities, and unresolved contractual obligations. Resolve these matters before proceeding wherever possible.If eligibility is uncertain, obtain professional advice before applying.
Step 2: Prepare the Company’s Records
Gather the information needed for the application. This usually includes the company’s registered details and director information.Review bank accounts, accounting records, and remaining company assets. Deal with these matters before dissolution.Company property requires particular attention. Assets remaining after dissolution may pass to the Crown as bona vacantia.Therefore, do not overlook bank balances, refunds, or intellectual property. Obtain suitable advice before transferring or distributing company property.
Step 3: Complete the Online Application
Use the official Companies House service to begin your application. Follow the instructions and provide accurate company information.Check the company’s name and registration number carefully. Errors can cause delays or require further action.Only an eligible person should submit the application. Directors should ensure that all declarations are accurate.You can check current guidance through the official Companies House website.
Step 4: Notify Interested Parties
Applicants must comply with the statutory notification requirements. Relevant parties generally include shareholders, creditors, employees, and other specified recipients.The required notification must usually be sent within seven days. This period runs from the application date.Check the current rules to identify everyone requiring notification. Keep evidence of the notifications and their dates.Failing to notify the correct parties can have serious consequences. It may also provide grounds for challenging the proposed strike-off.
Step 5: Wait for the Companies House Decision
Companies House publishes a notice concerning the proposed strike-off. This gives interested parties an opportunity to raise objections.A creditor or another eligible party may object. Companies House can suspend the process while an objection remains unresolved.If the application proceeds, a final notice is published. The company is then dissolved on the date stated in that notice.Do not assume the company has closed immediately after applying. Check the register to confirm the final dissolution.
How Much Does It Cost to Dissolve a Company?
The cost depends on the closure method and the company’s circumstances. A straightforward voluntary strike-off is usually less expensive than liquidation.Companies House charges a fee for voluntary strike-off applications. The applicable amount can change, so check the official fee schedule.Additional costs may arise from accounting or tax work. Professional fees may also apply when resolving debts or legal issues.A company with complex finances may require specialist assistance. An insolvent business could face substantially higher closure costs.Consider the full cost before choosing a closure method. The cheapest option is not always the most appropriate.
How Long Does Company Dissolution Take?
The timeline depends on the application and any objections. Straightforward applications can take several months to complete.Companies House must follow the statutory notice process. Delays may occur if information is incorrect or objections arise.Outstanding tax matters can also complicate preparations. Therefore, allow sufficient time for each stage.Check the latest Companies House guidance for current processing information. Avoid making firm plans around an unconfirmed dissolution date.
Common Mistakes to Avoid When Dissolving a Company
Small oversights can create substantial difficulties during company closure. Understanding common mistakes helps you prepare more effectively.
Applying Before Settling Company Affairs
Some directors apply before reviewing outstanding liabilities. This can lead to objections or later legal complications.Settle debts and conclude business affairs where appropriate. Seek advice if the company cannot meet its obligations.
Ignoring HMRC Requirements
Tax responsibilities do not disappear simply because trading has stopped. Outstanding returns or payments may complicate the closure.Contact HMRC and establish what remains necessary. Keep copies of returns, payment records, and relevant correspondence.
Forgetting About Remaining Assets
Directors sometimes overlook balances, equipment, refunds, or other property. Assets remaining after dissolution can become bona vacantia.Review the company’s assets before submitting the application. Follow appropriate procedures for lawful distributions and transfers.
Failing to Notify Relevant Parties
Notification requirements form an important part of the process. Failure to comply can undermine the application.Create a list of everyone requiring notification. Keep evidence showing when and how notices were sent.
Assuming Dissolution Removes Every Risk
Dissolution does not guarantee that all future claims become impossible. Certain circumstances may allow a company to be restored.Directors may also face consequences for misconduct or breaches of duty. Take care when handling debts, records, and company assets.
Can a Dissolved Company Be Restored?
In some circumstances, a dissolved company can return to the register. This process is commonly called company restoration.Administrative restoration may be available when specific statutory conditions apply. It is generally associated with certain companies struck off by Companies House.Court-ordered restoration may be necessary in other circumstances. Eligibility depends on the facts and applicable legal requirements.Restoration can involve filing outstanding documents and paying relevant fees. Outstanding obligations may also need to be addressed.This possibility makes careful closure particularly important. Directors should ensure the original strike-off process is handled correctly.
Should You Use a Professional to Dissolve a Company?
Some company closures are simple enough for directors to manage themselves. Others involve financial, tax, or legal complications.Professional support may help identify the correct closure procedure. An accountant can assist with final accounts and tax matters.A solicitor may help with contractual or legal concerns. An insolvency practitioner can advise when financial difficulties exist.Choose support based on your company’s actual circumstances. Professional advice can be particularly valuable when liabilities remain unresolved.
Frequently Asked Questions
Can I dissolve a company online in the UK?
Yes, eligible companies can apply through the Companies House online service. You must satisfy the relevant conditions and provide accurate information.
How do I strike off a company?
First, check eligibility and conclude outstanding company affairs. Submit the appropriate application and notify relevant parties as required.Companies House then follows the statutory notice process. Dissolution occurs only when the final notice takes effect.
How much does it cost to dissolve a company?
The cost depends on the application method and company circumstances. Check the current Companies House fee before submitting an application.Accounting, legal, or insolvency services may involve additional charges.
Can I dissolve a company with outstanding debts?
Outstanding debts can lead to objections and legal complications. Directors must not use strike-off to avoid legitimate creditor claims.Seek professional advice if your company cannot pay its debts. Formal insolvency proceedings may be more appropriate.
How long does it take to dissolve a company?
The process commonly takes several months, depending on the circumstances. Objections, incomplete information, and unresolved issues can cause delays.Check Companies House guidance for current processing expectations.
What happens to company assets after dissolution?
Remaining assets may pass to the Crown as bona vacantia. This can include money, property, and certain other assets.Deal with company assets properly before dissolution. Obtain advice if ownership or distribution is unclear.
Can I start another business after dissolving my company?
Generally, dissolving a company does not prevent you starting another business. However, you must comply with applicable legal obligations.Check any restrictions involving insolvency, director disqualification, or other proceedings. Take advice if your circumstances raise specific concerns.
Can a dissolved company be brought back?
Yes, restoration may be possible under certain statutory procedures. The appropriate route depends on how the company was dissolved.Administrative restoration and court-ordered restoration have different eligibility requirements. Obtain advice before starting the restoration process.
Conclusion
Choosing to dissolve a company requires careful preparation and informed decisions. UK directors must follow the correct procedures before closing their businesses.Voluntary strike-off can provide a practical option for eligible companies. However, it is not suitable for every financial situation.Review your debts, tax obligations, contracts, and remaining assets first. Submit accurate information and notify everyone required by law.If insolvency or legal complications arise, seek professional advice. Taking these steps can help you close your company responsibly and confidently.